Why a Simple Money-Records Habit Matters More Than a Tax-Time Rush
A guest piece on why a weekly recordkeeping habit beats a tax-time scramble, for anyone whose income comes from more than one place.
By Junior O. Osiemi, Guest writer
Why a Simple Money-Records Habit Matters More Than a Tax-Time Rush
When people talk about improving their finances, the conversation often starts with earning more, finding deductions or making a clever investment. I think a quieter habit deserves more attention: knowing where the money went and keeping the records that explain it.
This matters especially for entrepreneurs, farmers, freelancers and anyone whose income arrives from more than one source. A business can be busy and still leave its owner uncertain about cash flow. Receipts may be scattered across messages, bank statements, notebooks and drawers. By the time a tax deadline approaches, the difficult part may not be the calculation. It may be reconstructing what actually happened.
The good news is that recordkeeping does not have to begin with expensive software or a complicated spreadsheet. It can begin with a small routine that a person can repeat.
Start with the question, not the app
Before choosing a financial tool, ask what you need to know. How much money came in this month? What did it cost to earn that money? Which expenses are personal and which relate to business? What payments are due soon? What supporting documents would help you explain a transaction later?
These questions are more useful than a dashboard full of numbers that no one understands. A simple spreadsheet, a paper ledger or an established bookkeeping tool can all help. The right system is the one you can maintain consistently, while meeting any recordkeeping requirements that apply in your country.
Keep business and personal transactions distinguishable
A common source of confusion is mixing everyday household spending with business purchases. When transactions are not clearly separated, a bank statement becomes a puzzle: Was that transfer income, reimbursement, a loan, a personal withdrawal or a customer payment?
Where practical, using a separate business account or payment method can make the story easier to follow. Where that is not possible, record the purpose of each transaction when it happens. A note written today is usually more reliable than a guess made months later.
Separation also helps with decisions beyond taxes. You can see whether the activity is generating enough cash to support its costs rather than treating every deposit as profit.
Give every transaction a short explanation
A receipt proves that something was purchased, but it does not always explain why. An invoice can show a sale, but it may not show whether the customer has paid.
For each meaningful transaction, record the date, amount, who paid or received the money, the purpose and the supporting document. Add a simple status such as paid, unpaid or reimbursed when useful. Keep records in a consistent location with a backup.
For farmers and other seasonal businesses, this habit can be particularly valuable. Spending on supplies may happen long before the related income arrives. Looking only at the current bank balance can hide the timing gap. A clear record of commitments and expected receipts gives a better picture of what is coming.
Set aside ten minutes before the paperwork grows
A financial system that depends on one exhausting weekend every year is easy to avoid. A brief weekly review is often more sustainable.
Once a week, compare recorded transactions with the bank or payment account. Match invoices to payments. File receipts. Flag unfamiliar charges and follow up on missing documents. Make a note of upcoming bills and money that customers still owe.
This is not a promise that every financial problem will disappear. It is a way to notice problems while there is still time to respond. A missing invoice discovered this week is easier to investigate than one discovered next year.
Remember that a deduction is not the same as free money
Tax language can create misleading expectations. A legitimate deduction may reduce taxable income, but it does not usually reimburse the entire purchase price. The effect depends on the applicable law, the nature of the expense and the taxpayer's circumstances.
That is why buying something solely because someone online calls it a "write-off" can be a poor decision. First ask whether the purchase is genuinely needed and affordable. Then ask whether it qualifies under the rules that apply to you. The answer may differ between countries, types of business and tax years.
No general article can determine whether a particular expense is deductible for an individual reader. For that, reliable official guidance and a qualified local tax professional are the right places to turn.
Build a decision file, not just a tax file
Good records are not only for a tax return. They can help a family or business decide whether to replace equipment, take on a new obligation or save for an uncertain period.
For a large purchase, keep the quote, estimated running costs, financing terms and the reason for making the decision. Later, compare what you expected with what happened. This turns an expensive choice into information you can use next time.
A decision file also helps separate fact from enthusiasm. It is easy to remember the promised benefit of a purchase and forget the maintenance, insurance, interest or time involved.
Protect the information you collect
Financial records can contain account numbers, addresses and other sensitive details. Use strong account security, limit who has access and keep backups in a secure location. Avoid sending full financial documents through unverified links or sharing personal details simply because someone claims to offer tax savings.
A trustworthy recordkeeping system is not just organised. It is private enough to protect the people and businesses it describes.
Choose one habit to begin this week
The most useful system is not necessarily the most sophisticated one. It is the one that makes next week's decisions easier.
Start with one folder for supporting documents and one place to record income and spending. Review both at a fixed time each week. As the routine becomes reliable, add the detail your situation requires.
Tax season will still require care, and professional advice may still be necessary. But with a record of what actually happened, the conversation can begin with evidence rather than a pile of guesses.
About the Author
Junior O. Osiemi is an entrepreneur and independent author who writes about financial literacy, responsible planning and long-term wealth protection. His book THE ZERO TAX BLUEPRINT explores lawful approaches to understanding taxes and making informed financial decisions.
Further Reading
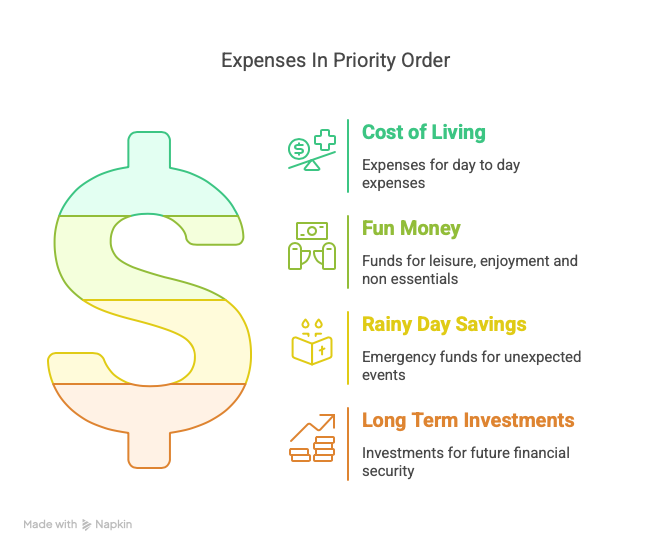 BlogHow to Manage Your Money with a Cash Flow ViewUnsure how to manage your money? Start with a plan for the life you want, then use a cash flow view to keep score.Read article
 BlogFinancial Data SecurityFinancial fraud is almost never a break-in. It is a polite request at a bad moment, and the single question that stops it.Read article
 BlogShould You Feel Guilty About Minimising Your Tax?A tax return reconciles what you paid against what you actually owed, and a refund is your own money coming back. Minimising your tax within the law is not a moral failing.Read article
Disclaimer: We are not financial advisers. The information on this website is general in nature and does not take into account your individual circumstances. You should seek independent professional advice before making financial decisions.