The Cost of Living Squeeze: See Where Your Money Actually Goes
Rents, mortgage repayments, groceries, insurance, power. The cost of living crisis is not in your head. Headline inflation is running at 3.8% and rising faster than that in the categories that hurt most. Most of what is driving it is not something you can do anything about this month.
What you can do something about is your own spending, and the honest problem there is that almost nobody can see theirs clearly enough to make good calls. “Just cut back” is not a plan when you do not know what you are spending in the first place.
By Patrick, Founder
Part One: Stop worrying about a problem you may not have and start thinking about a solution to the problem you do have.
The part you can’t control, and the part you can
You do not set interest rates. You cannot negotiate your rent down to last year’s number or opt out of the energy market. Those levers belong to other people, and the news will keep reminding you of that.
The one lever that is entirely yours is what leaves your account each month. It is also the one most people cannot describe with any accuracy. Ask someone what they spent on food, subscriptions or eating out last month, and the answer is usually a guess, and usually low. You cannot make a good decision about a number you are guessing at.
You can’t cut what you can’t see
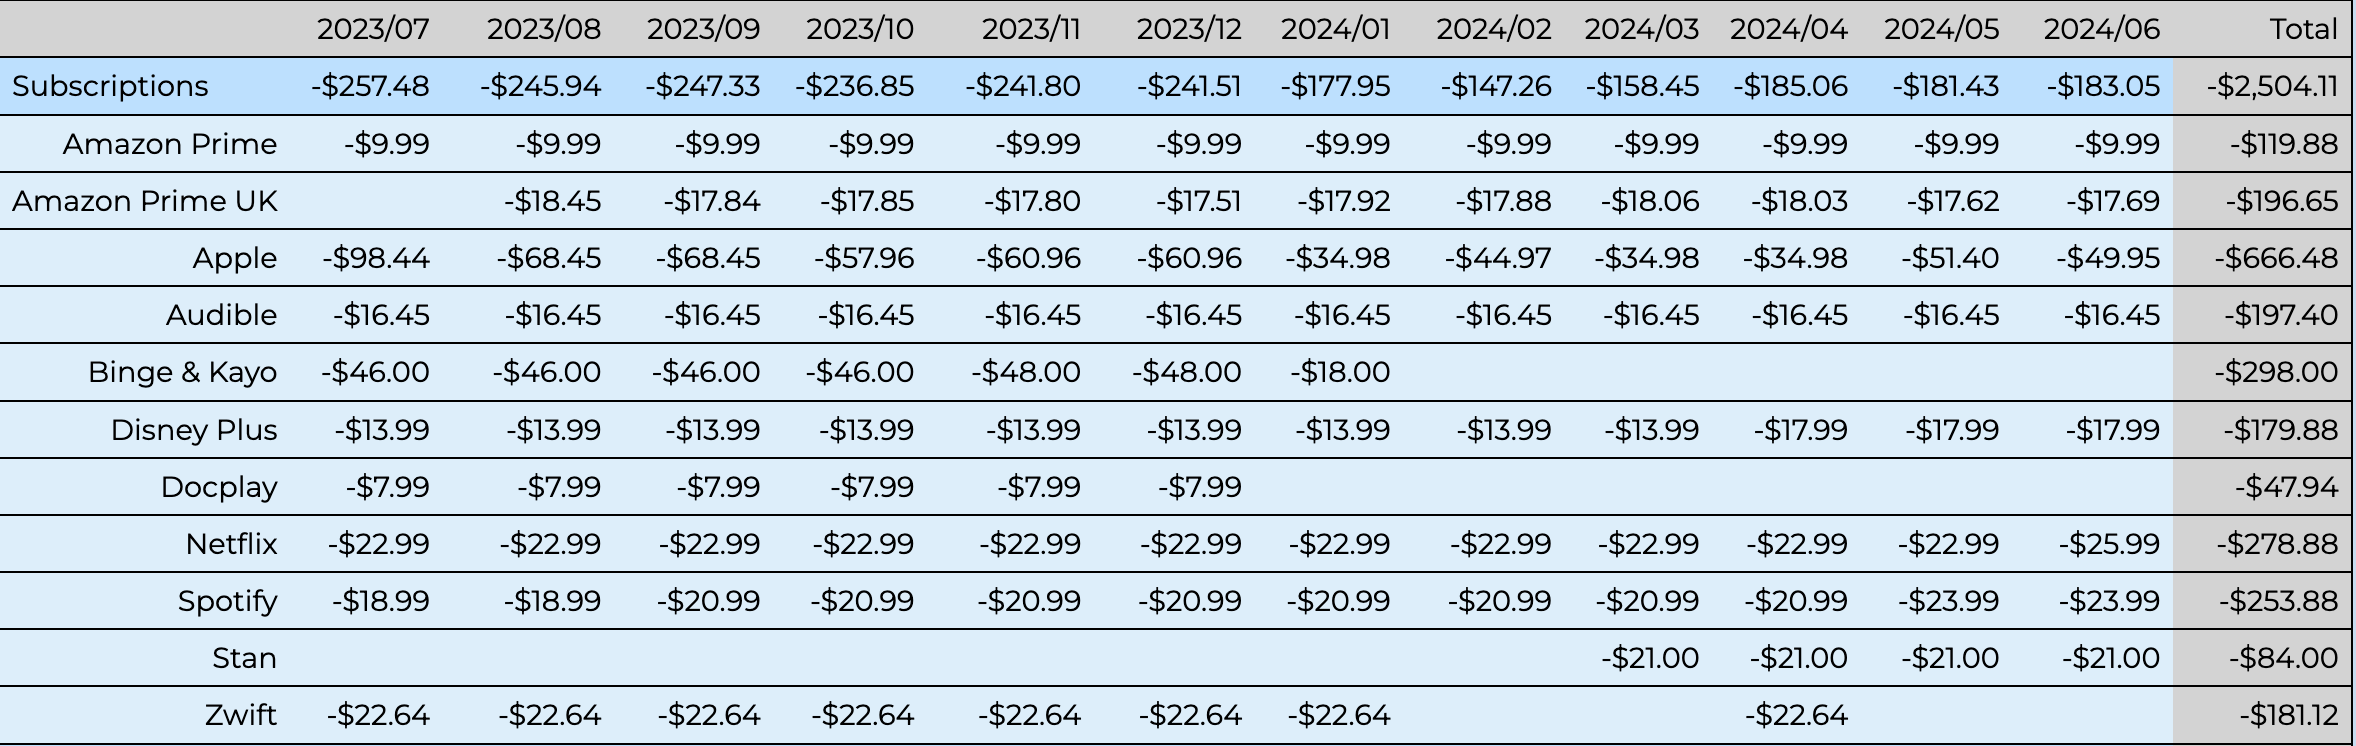
“Where does my money go?” takes your bank transactions and turns them into a single cash flow table: money in and money out by category, by month, side by side. The year of transactions becomes one page you can understand clearly in a few minutes.
That is the bit that changes the conversation. Instead of “we should spend less,” you are looking at “$740 a month on groceries, $210 on subscriptions and streaming, $460 on takeaway and coffee, $180 on things I would struggle to name.” The categories are yours to define, through simple rules, so the table matches how you actually think about your money. That’s the important bit: it has to be clear to you, so that you can think about it and what decisions you are willing to make.
Deciding what you’re actually willing to lose
Most cost of living advice hands you a list of what you should cut. That is not how it works in a real household. Some people will drop every subscription before they touch the weekly coffee; others will do the reverse. The point of seeing the numbers is that you get to make that trade deliberately, with the size of each choice in front of you.
A few things the table tends to surface:
- Small recurring charges that add up to more than the occasional big purchase you feel guilty about.
- Annual and quarterly bills, such as insurance, rego and rates, that never show up in a “typical month” and blow up the budget when they land.
- Categories where the number is simply higher than you thought, which is usually where the easiest cuts are.
The app does not budget for you or tell you off. It shows you the picture and leaves the decision where it belongs, with you.
Keep a buffer for the lumpy stuff
Cutting is only half of it. The other half is not getting knocked over by the irregular costs, such as a car repair, an excess, or a rate rise you had not budgeted for. A modest cash buffer is what stops a bad month turning into new debt, which is the last thing you want when money is already tight. How much you actually need in a rainy day fund depends on your real cost of living, which is, again, the number the cash flow table gives you.
How it works
- Export your transaction file from your bank. Linking your bank login is not required.
- Use the interactive tools to categorise your income and expenses within the cash flow table. Within the cash flow table there are categories and subcategories, and as a guide these should be things that you can change. For example, there is little value in having a subcategory for every takeaway you eat from, but there is value in seeing how much you spend on takeaways.
- Open the cash flow table and read your entire year of income and expenses in a few minutes. Examine this and check that:
- You are living within your means, so your expenses are less than your income.
- You are spending your money in the most optimal way for you. That may be on investments, holidays, going out, or whatever. What matters is that you think deeply about that and ensure it is in a way that you feel benefits your life the most.
- Come back monthly. You should ensure that you have the latest figures, because situations change all the time. You should also check that any changes you did put in have actually resulted in the outcome that you wanted.
None of this makes rent cheaper. It makes the one part of the problem you control something you can actually act on, instead of something you are guessing at.
Part Two: How you can take advantage of and succeed during a cost of living crisis.
What is actually driving Australia’s cost of living crisis?
“Inflation” is the shorthand, but it lands unevenly. Some of your bills have barely moved and others have jumped, and the average hides that. Here is where the pressure is concentrated right now.
Housing is the heavy one, and it splits. If you rent, it is the rent itself. If you have a mortgage, it is the run of rate rises still working through your repayments. On top of that sit insurance premiums, energy, and the weekly shop. If your pay has moved up a little while three or four of those have moved up a lot, the squeeze is real even though the headline number sounds modest. Here is why prices rise in the first place and why a “low” rate can still hurt.
Twenty years of inflation, interest rates and the market
Inflation and the RBA cash rate move together. The rate is the main tool used to pull inflation back down. What is striking is the third line: through every rate cycle and the 2022 spike, the share market kept climbing. The people who came out ahead were mostly the ones who owned assets and held debt. Cash did the opposite.
How you actually get ahead of it
The chart holds a blunt lesson. Over the two decades, the same three things kept happening:
- Assets rose with inflation. Property and shares had bad years, but across 20 years they climbed well ahead of prices.
- Fixed debt shrank in real terms. A loan set at a fixed rate got easier to carry every year that wages and prices rose around a repayment that did not move.
- Cash lost, every year, guaranteed. Money left in a low interest account bought a little less each year with nothing to show for the wait.
The households that came out ahead were not smarter. They were positioned by holding some assets, carrying some fixed debt, and not sitting on more cash than they needed.
In the middle of a squeeze, “own assets” can sound like advice for someone else, and it is harder now than it was. But two things are worth knowing. If you have super, you are already on the winning side of part of this whether you think about it or not. That money is invested, and it has been riding the same climb as the chart’s third line. And the one move fully within reach is the boring one: see where your money goes, find the margin, and use it so you are not left entirely in cash and entirely behind, which is exactly what the cash flow view earlier on this page is for. Building on that margin is a separate question, but you cannot get there while the money is invisible.
Disclaimer: We are not financial advisers. The information on this website is general in nature and does not take into account your individual circumstances. You should seek independent professional advice before making financial decisions.
Feeling the squeeze?
Work Out What You Can Cut
Start a 28-day free trial and turn your bank exports into one cash flow table, and see the size of every choice before you make it.